Best Credit Cards in Germany in 2026 – Guide for Expats
Transparency
How we earn our money
We finance our services on how-to-germany.com through affiliate programs.
When a user orders a financial product through our site and their application is approved, we may receive a commission from some providers. It’s important to note that this does not in any way influence our independent ratings and recommendations.
All the products we present on how-to-germany.com are selected for their quality, range of services, and excellent value for money.
Credit Cards in Germany – Guide for Expats
Which credit card you get in Germany depends on your Schufa record. Newcomers get the TF Mastercard Gold more easily than most cards – no annual fee and no foreign currency fees, but interest on cash from the day of withdrawal. With an established credit history, American Express cards add rewards and travel insurance.
Written by
Janine El-Saghir
Janine El-SaghirJanine El Saghir is an editor at How-to-Germany.com, where she specializes in the practical aspects of daily life and integration for expatriates. With years of...Read more
Reviewed by
Erkan Boga
Erkan BogaErkan Boga is the founder and CEO of qmedia GmbH, the publishing house behind How-to-Germany.com. He established the platform with the clear vision of creating...Read more
Edited by
Sadie Voss
Sadie VossContent Lead & EditorSadie Voss is the Lead Editor for How-to-Germany.com. As an expat who carved her own way into Berlin from the United States, Sadie is deeply...Read more
Best Cards for Newcomers - Low-Cost
Best Cards for Established Expats - Rewards & Travel
Advertising notice: provider links in this overview are affiliate links — we receive a commission from the provider for sign-ups made through them.
We are independent from the providers of the financial products that we test and evaluate.
We are transparent regarding our research processes and evaluation methods.
Our content undergoes careful quality check to ensure that it is well-researched, factually correct, and understandable.
We have 18+ years of experience with financial products. Our recommendations and evaluations are based on sound specialist knowledge. In addition, we have our life experience as expats, and we know first-hand what expats in Germany want and need.
Best Credit Cards in Germany: At a glance...
With a charge credit card, you repay your full credit card bill each month — without any interest, if you make timely payments. Revolving credit cards allow you to borrow money for a longer period and let you pay in installments, albeit with interest. In addition to genuine credit cards, you can also choose between debit cards and prepaid cards without an overdraft function.
Your Schufa score (credit rating) decides what credit card and credit limit you can get.
New in Germany? Look at the TF Mastercard Gold – a free credit card with repayment options in monthly installments, travel insurance, discounts, and a mobile banking app in English. The TF Mastercard Gold is the best credit card for starters in Germany.
If you’ve been in Germany for a while and have a regular income and a good Schufa record, the American Express cards open up: the Blue Card has no annual fee, the Gold and Platinum Cards add travel insurance and Membership Rewards points. American Express cards are charge cards — the balance is settled in full every month.
Miles and rewards programs aren’t as prevalent in Germany. If you fly a lot, look at Lufthansa or Eurowings credit cards, which are part of the Miles & More program. The American Express credit cards also offer an excellent rewards program. For shopping cashback, consider American Express Payback, but note that American Express isn’t as widely accepted as Visa or Mastercard.
Tip
If a credit card provider’s site is only in German, use Chrome’s auto-translate (right-click → “Translate to English”). If buttons or links don’t respond well in the translated version, switch back to German and try again.
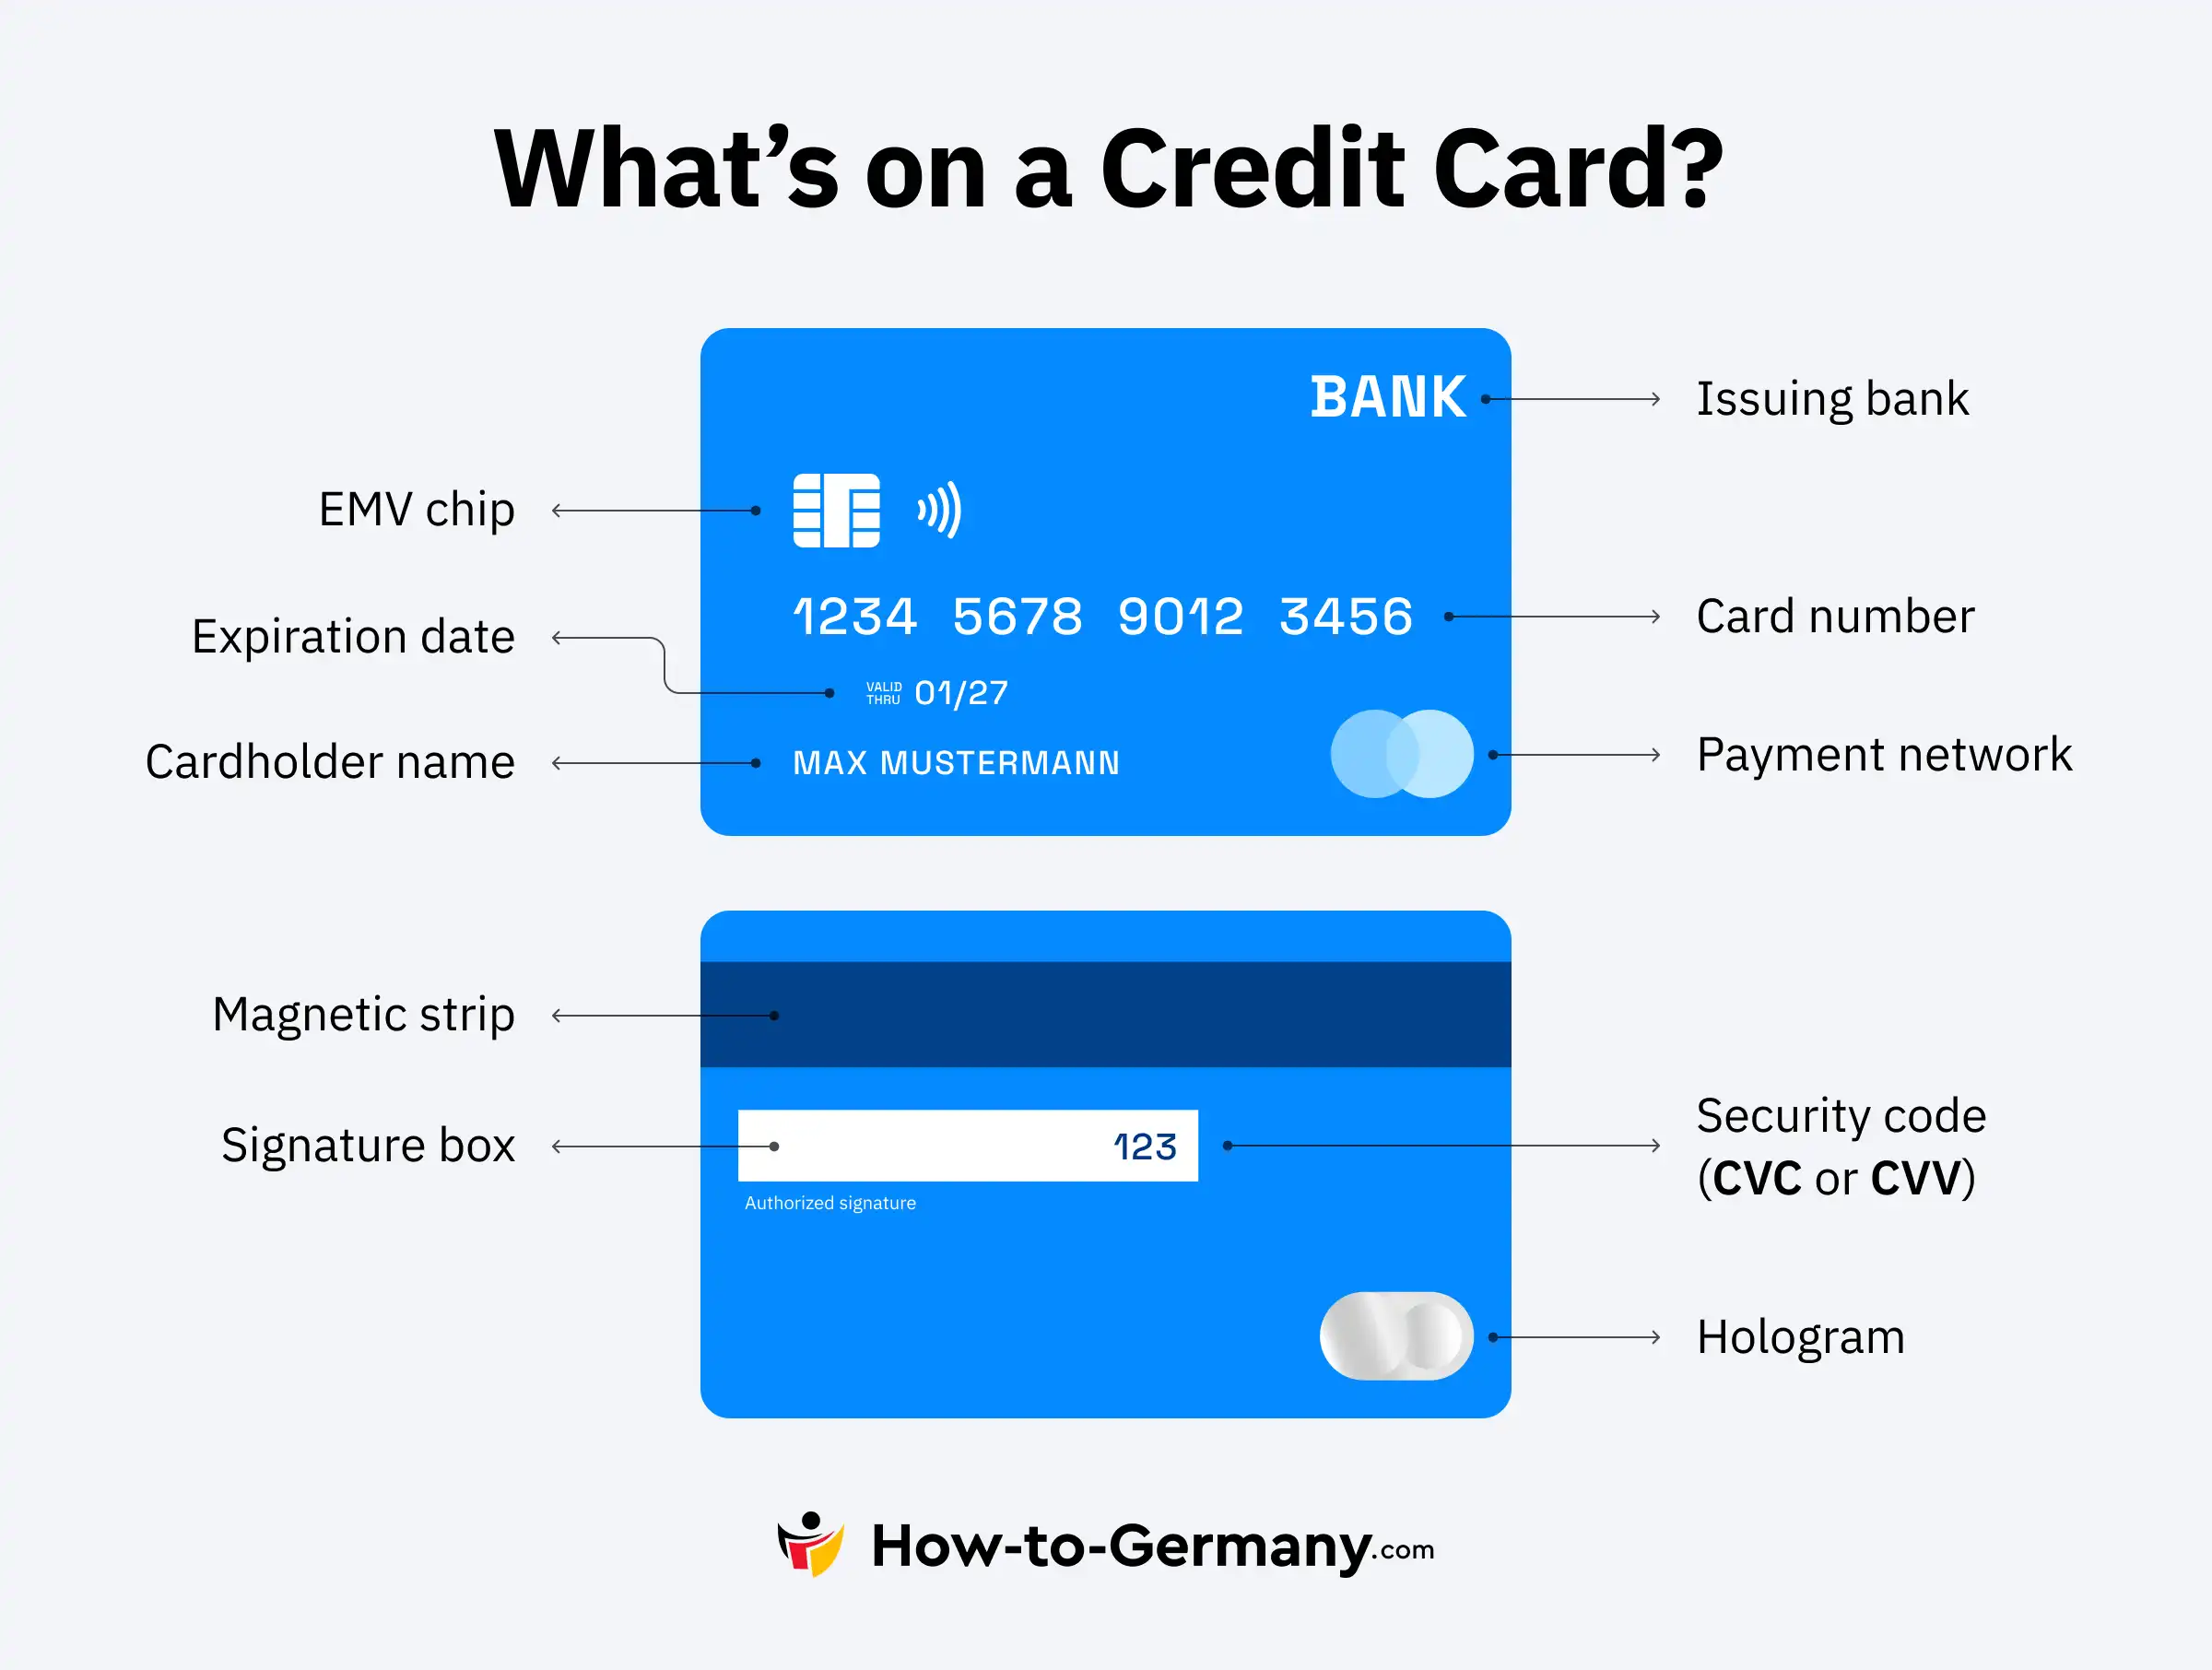
There are 4 different types of credit cards in Germany: revolving credit cards, charge credit cards, prepaid credit cards, and debit cards. Each has its unique features and benefits tailored to different user needs. Understanding the various credit card types is crucial for selecting the best option for your needs as an expat.
There are numerous credit card offers in the German market designed for different needs. Our credit card comparison focuses on the needs of expats, highlighting flexibility, accessibility, and long-term costs.
Revolving Credit Card — Monthly Billing and Option for Installment Payments
A revolving credit card is the only true credit card that gives owners a credit line and the possibility to pay back in monthly installments.Photo: iStock.com/Viorel Kurnosov
In Germany, the term “Kreditkarte” describes all varieties of credit cards. However, revolving credit cards stand out as the only “real” credit cards in the classical sense. With this card, all purchases are combined over a month, and the user receives an interest-free payment period of approximately 4 weeks. Depending on the German credit card provider, this period might be longer. With the easybank Visa credit card, for example, it is up to 59 days.
After this time, credit card users can decide whether to pay the total amount due, without interest rates, or in installments. If they opt for installments, they’ll be charged interest based on a percentage of the outstanding amount. This kind of loan is more adaptable than a fixed-term loan. However, you should always expect a high interest rate for a revolving credit card. Late payments of the full amount also incur interest.
Credit card providers require a minimum monthly repayment — either a percentage of the outstanding balance or a fixed amount. Depending on the provider, repayments can be made manually via SEPA transfer or direct debit.
Due to their installment payment feature, revolving credit cards are often only provided to individuals with a clean credit history, a stable income, and no negative records. Applicants with a good credit score generally have better chances of approval and may also receive higher credit limits.
Prepaid credit cards or debit cards are often more suitable for individuals with unstable earnings, students, and newcomers without a financial history in Germany.
Charge Credit Card — Monthly Deduction of Accumulated Charges
With charge cards, you borrow money for a short period only. The credit card company sends a monthly bill and then automatically takes the due amount. This provides a short-term “loan” without interest of up to 4 weeks, allowing you to make purchases even if you don’t have sufficient funds in your account yet. Please ensure that you have enough money in your checking account at the end of the billing period to repay the full amount. Otherwise, additional costs may be incurred. Repeated late payments may also result in the cancellation of the card.
Unlike revolving credit cards, with a charge credit card, you typically cannot pay in installments. The total amount is taken all at once. However, sometimes arrangements can be made with the credit card provider.
Most credit card providers offer either revolving credit cards or charge cards, so your choice of provider will also depend on which type of credit card you prefer.
Prepaid Card — Requires Preloading the Card Account
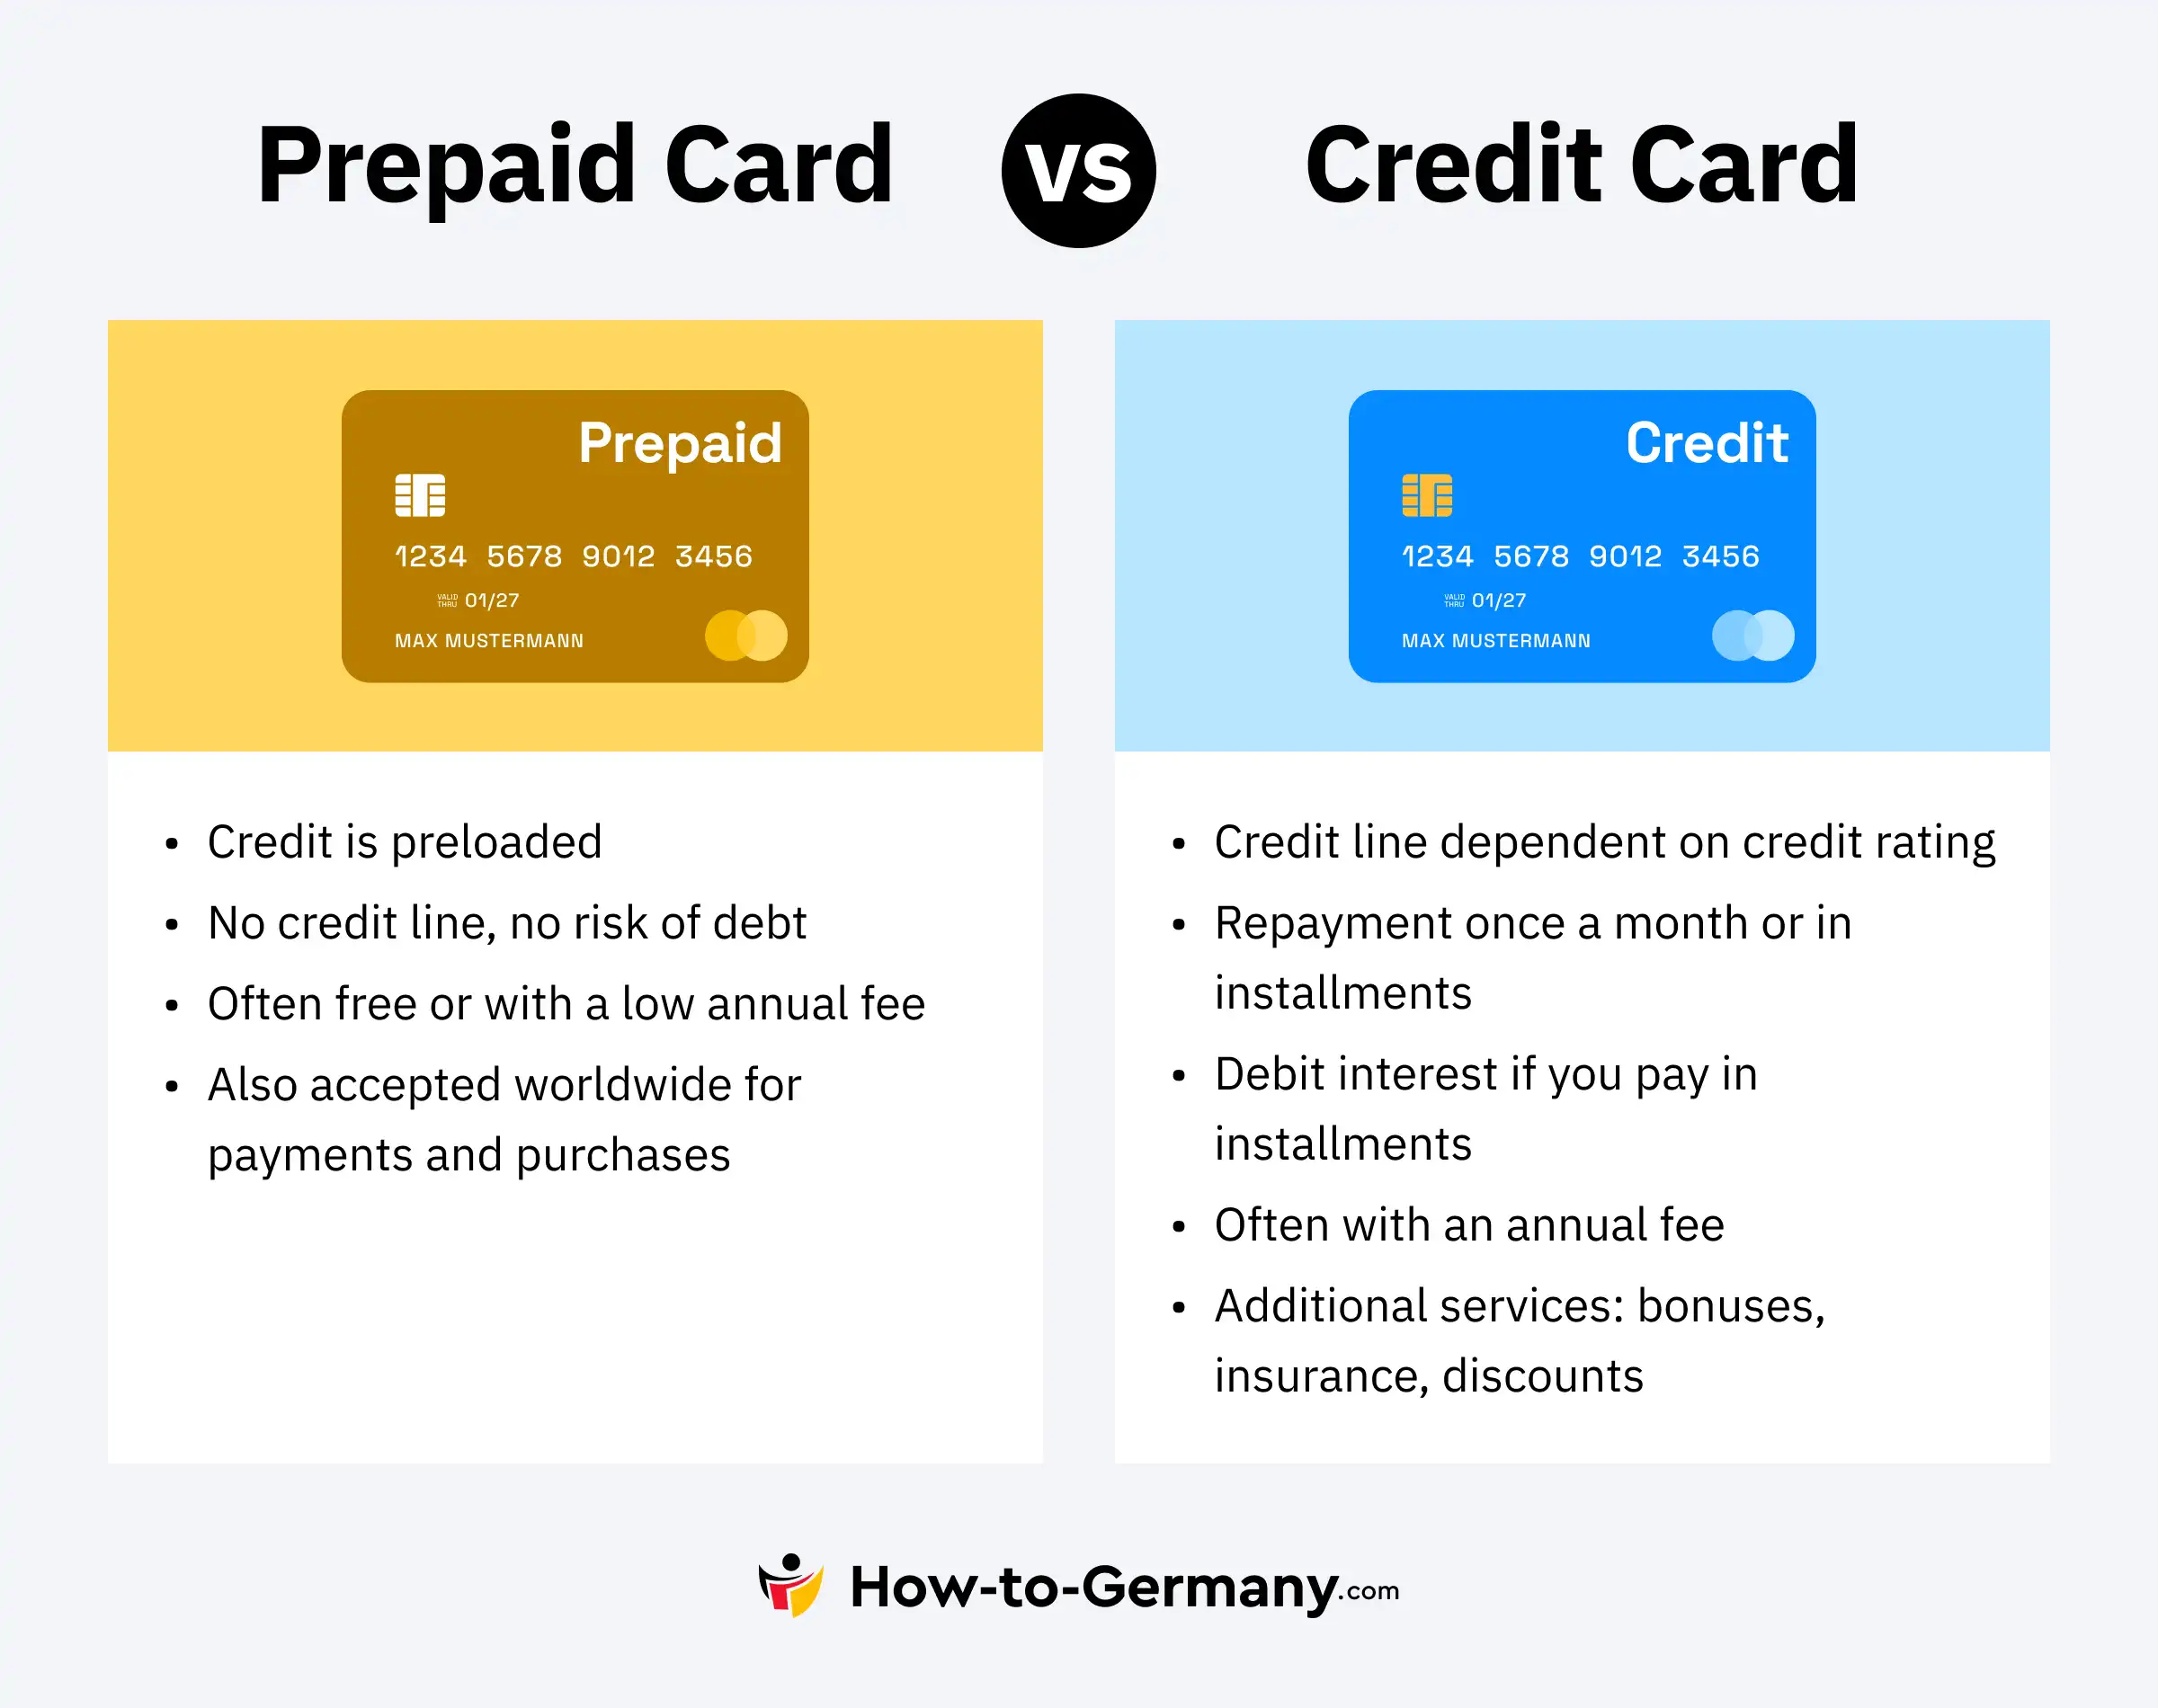
A prepaid credit card isn’t like a typical credit card. It only works if you’ve added money to the credit card account beforehand. Think of it as refilling a mobile phone: you can use it as long as there’s a balance. Without funds, the card won’t work until reloaded.
For students or those with fluctuating income who can’t get a standard credit card, prepaid cards can be a great choice. They offer control over expenses since you can only spend what you’ve loaded. There’s no risk of unexpected debt or overspending. Additionally, if someone steals the card, they can only use the amount loaded onto it, making prepaid cards a secure payment method.
Prepaid cards are issued as Visa or Mastercard. They enable card payments and cash withdrawals worldwide.
Note that some rental car companies, hotels, or online platforms may not accept prepaid credit cards, as they don’t include a credit line.
Debit Card — Direct Deductions from the Bank Account
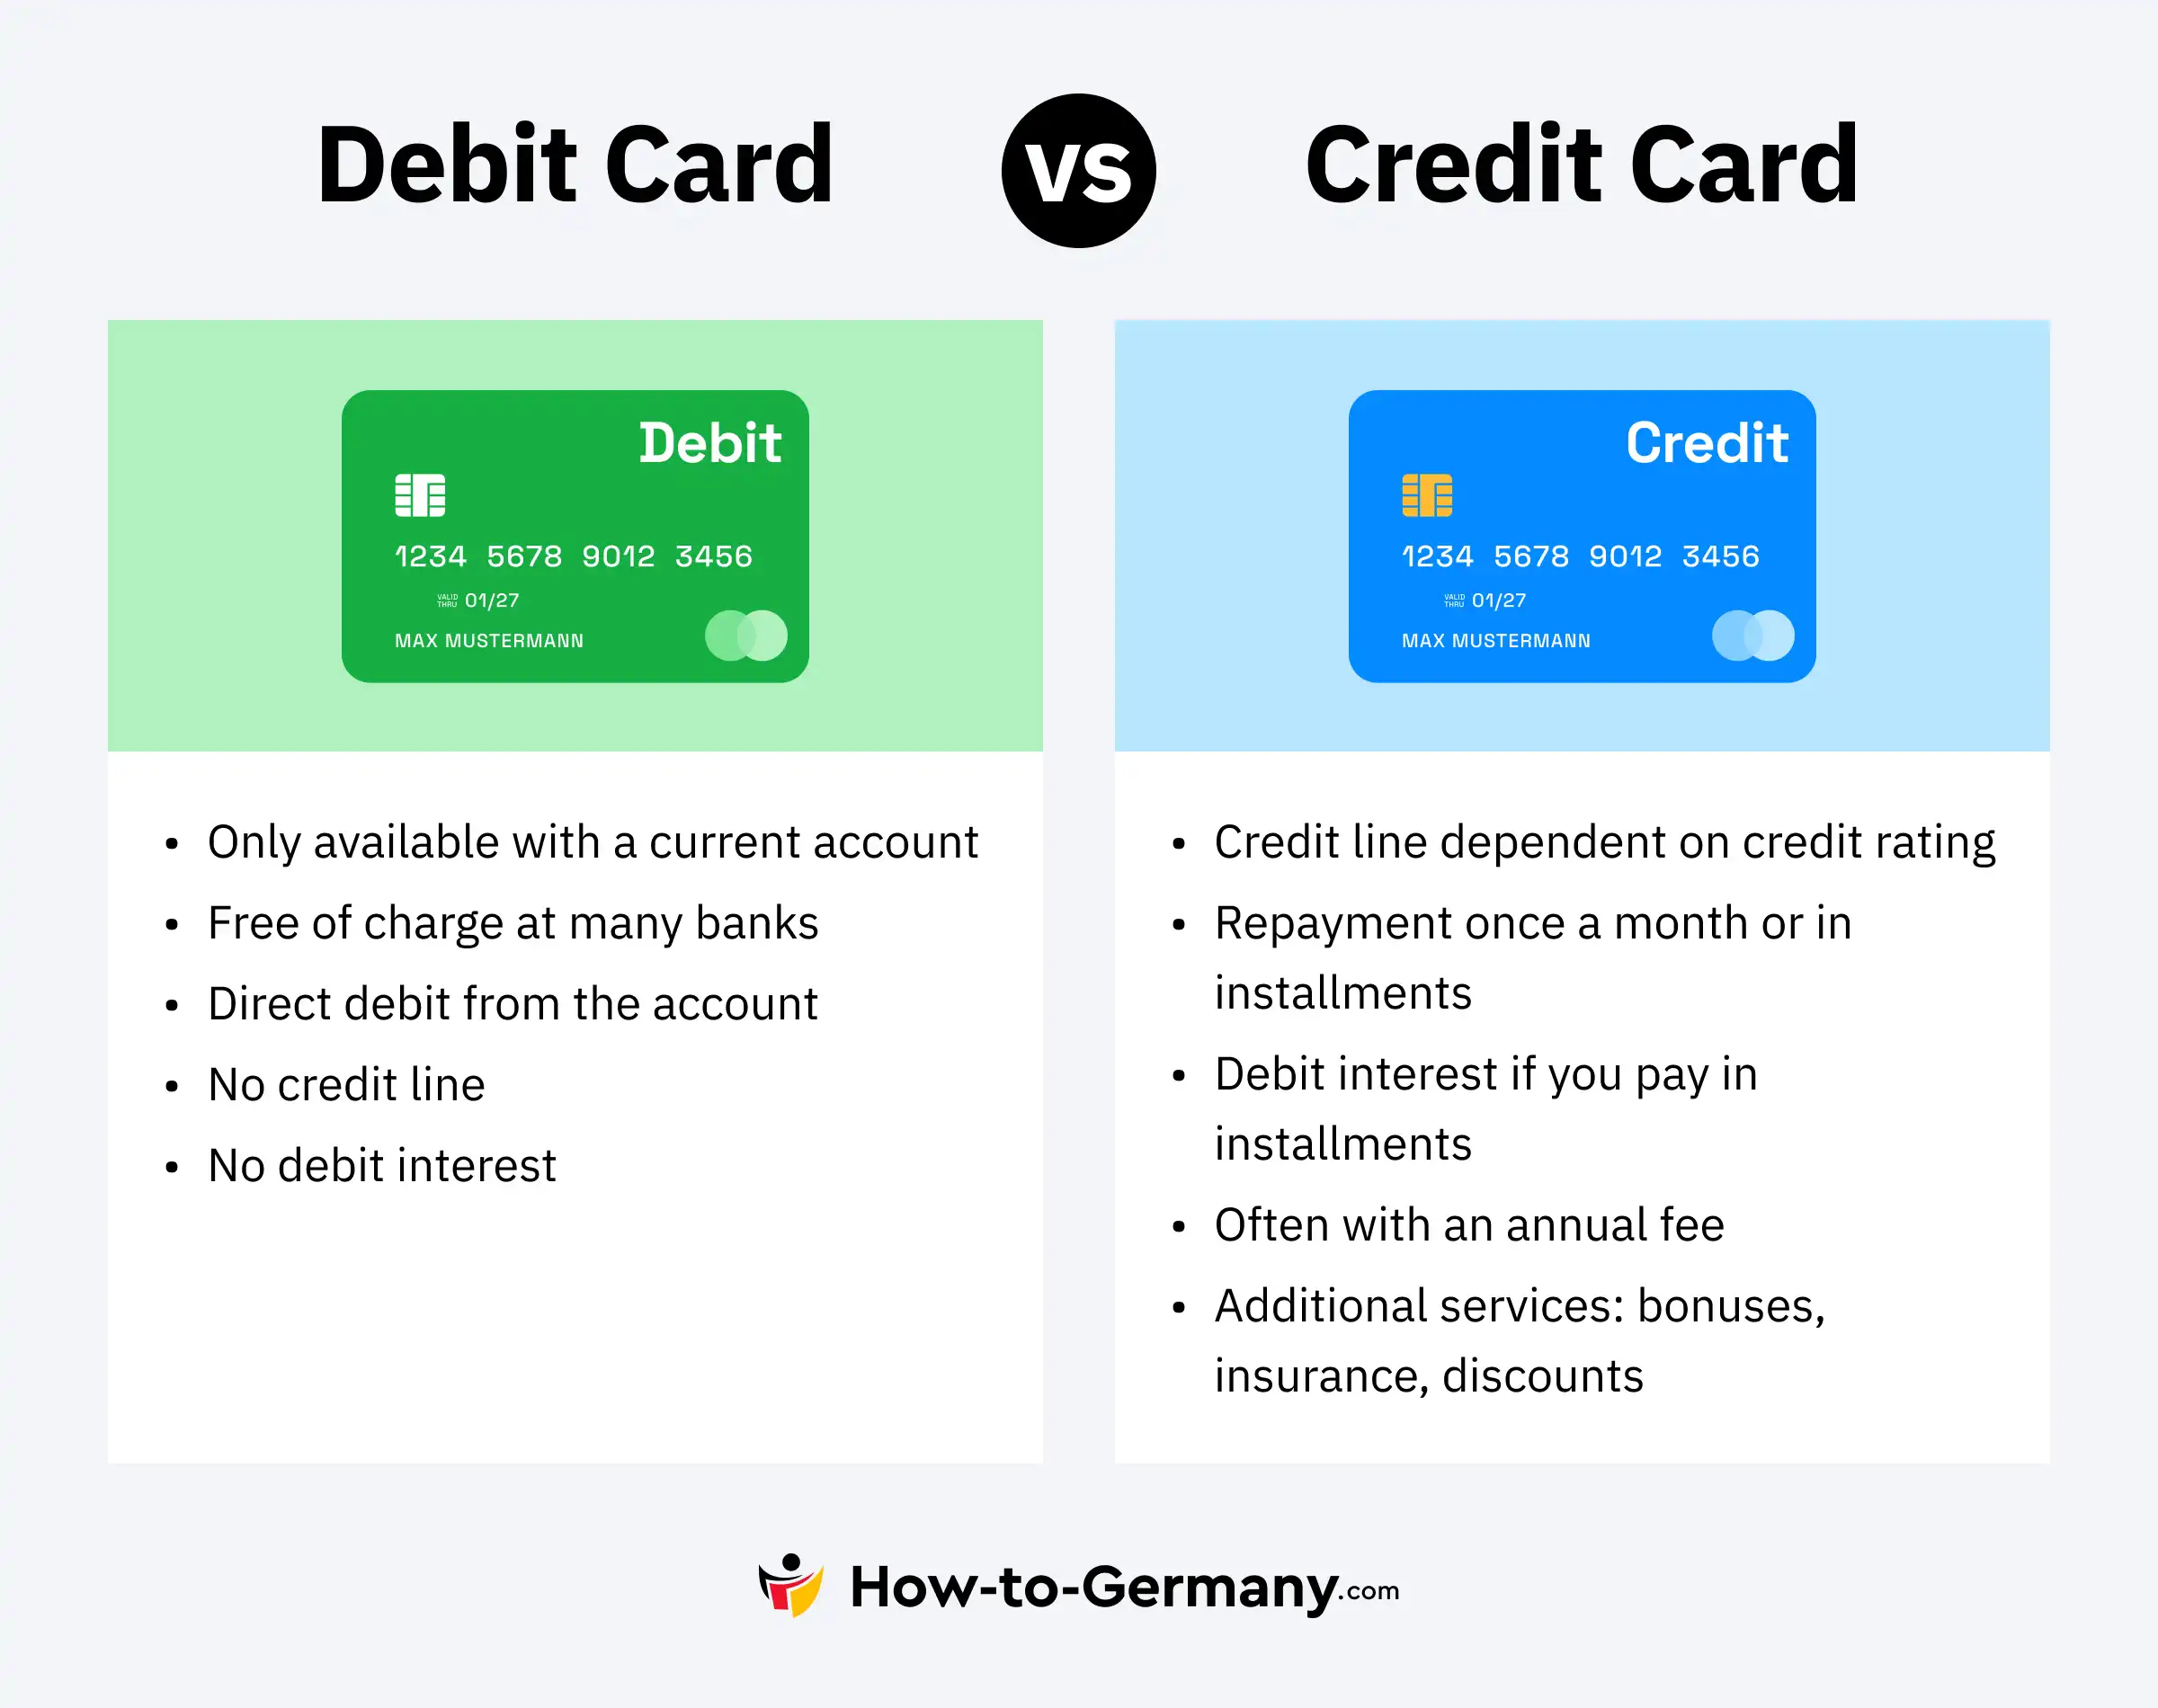
Using a debit card, the amount for any purchase or service is taken immediately from the linked current account. Unlike credit cards, debit cards don’t offer credit. However, you can still use them for many functions that a credit card offers: withdraw cash, make contactless payments, and make online purchases. Debit cards aren’t standalone; they’re always associated with a checking account. They’re ideal for those who want a direct overview of their spending and frequently make online payments. Modern debit cards feature the Visa or Mastercard logo and can be used worldwide.
The Schufa Check and Its Impact on Credit Card Applications
In Germany, anyone can apply for a credit card, provided they meet certain basic requirements, including being a resident of Germany and legal age. Beyond these basic criteria, credit card providers often have additional conditions that applicants must satisfy to get a credit card. Therefore, the type of credit card you can obtain usually depends on your credit history in Germany.
When applying for a German credit card with a credit limit, banks consider this a potential risk. To evaluate this risk, they conduct a credit check to assess the applicant’s payment history data. This data is sourced from Germany’s largest credit reporting agency, Schufa.
If you have a negative Schufa record due to serious payment delays or similar reasons, you may not be approved for this credit card. The bank must ensure that the customer can repay any borrowed money promptly.
However, debit and prepaid cards are often issued without a prior Schufa check. Since these cards don’t offer actual credit, they don’t pose a significant risk to the bank. Yet, they still provide users with the essential features of a credit card, including cashless transactions and ATM cash withdrawals.
Fees associated with German Credit Cards
Deciding what is the best German credit card for you is determined by your needs and financial goals.Photo: iStock.com/Jcomp
With a classic revolving credit card in Germany, holders must consider interest when using the flexible repayment option. Specifically, if the credit card bill is not fully paid within the interest-free period, a longer repayment period or installment plan is chosen instead. Interest rates can vary significantly depending on the credit card company.
There can also be additional fees when using the credit card outside Germany or when making cash withdrawals from ATMs. Some providers offer free paymentsand withdrawals in the eurozone and abroad, depending on the card type.
Beyond these fees, some credit card providers may also have an annual fee, which can vary significantly.
Annual Fee
Not every credit card has an annual fee. Typically, cards that offer more than the basic features charge this fee. These additional features can range from discounts and bonus programs to insurance benefits, such as travel or rental car insurance. The more features a credit card has, the higher the annual fee tends to be. In most cases, a premium credit card comes with a high annual fee but also offers numerous benefits, such as insurance packages, exclusive access, and cashback programs.
Cards that offer many high-quality features often come with a high annual fee. If these extra features are not useful to you, it’s better to choose a standard credit card to save money. While some benefits, such as insurance or discounts, can save money, they’re only beneficial if utilized. For instance, if someone travels only once a year, travel insurance or a frequent flyer program may not be useful. But for frequent travelers, these features can offer great value. However, there are also some free credit cards on the German market that offer additional benefits. If a card with high benefits comes without an annual fee, check whether it is waived for the first year as part of a promotion.
Even free credit cards without an annual fee might incur other fees for card transactions. Therefore, it’s always a good idea to review the terms or contact the credit card provider to inquire about all potential fees before obtaining a card.
Foreign Currency Fee
When using credit cards outside the countries of the eurozone, credit card providers such as VISA, MasterCard, American Express, and Diners Club are very useful due to their wide global acceptance. They can be used almost anywhere. When you pay or withdraw cash in a foreign country, the transaction is processed in the respective national currency. For this convenience, many credit card providers charge a fee for transactions in foreign currencies.
The foreign currency fee can vary a lot, typically ranging from 1% to 5% of the transaction amount. On average, however, most banks charge a surcharge of 1% to 3% for payments made in a foreign currency. If you travel frequently, a no-foreign-fee credit card is a good option to avoid extra charges. Otherwise, these fees can add up quickly over time.
Cash Withdrawal Fee
Credit cards are a widely accepted form of payment. They are practical, especially when you don’t have exact change at the checkout or for online shopping. Yet, there are times when cash is preferred or necessary. Fortunately, credit cards also allow you to withdraw money.
The fees for withdrawing cash using a credit card depend on the provider. The amount they charge can vary. Some credit cards offer free cash withdrawals worldwide, which is especially useful when traveling. Other credit card providers permit a certain number of free cash withdrawals per month or year, and then charge a fee for any additional withdrawals. Others may only allow free cash withdrawals at their bank’s ATMs.
It’s also crucial to note where the free cash withdrawals apply. With some credit cards, you can withdraw money without any fee worldwide. With others, free withdrawals might be limited to Germany or countries within the eurozone. And there are credit cards that don’t offer free cash withdrawals at all.
Please note: Any additional fees charged directly by the ATM company are separate from the credit card provider and are not included in the credit card fees.
Interest Rates
Genuine credit cards provide a monthly credit limit to cardholders. Traditional credit cards also offer the option to repay the borrowed amount in monthly installments. When cardholders choose this repayment method, they are required to pay interest on the borrowed amount. Typically, the interest rate for credit cards is variable and is charged only on the borrowed amount, not the entire credit limit.
For a credit card comparison, it’s essential to focus on the effective annual interest rate rather than just the nominal or borrowing rate. The effective annual interest rate provides a comprehensive view of the total interest costs, whereas the nominal rate only indicates the monthly interest charge, making it appear lower.
Best Free Credit Cards for Beginners
These fee-free cards are ideal if you’re starting a new life in Germany and need simple, flexible tools. They are much easier to get than the other ones, and still allow users to save money on fees and travel expenses.
This doesn’t necessarily mean you’re automatically approved when you apply. But you have a better chance of getting approved with these credit cards than with the others. They are some of the best free options for newcomers who want to avoid additional fees and enjoy extra services. However, you pay a high interest rate if you opt for the installment function.
TF Mastercard Gold
The TF Bank Mastercard Gold is the best credit card for beginners in Germany, ideal for new expats with limited credit history. It comes with no annual fee, no foreign currency fees, and no flat ATM withdrawal fees. However, cash withdrawals accrue interest immediately from the day of the withdrawal. The card offers travel insurance and cashback on travel and rental car bookings. Just remember to cover at least 50% of the travel booking with the card to get the insurance benefit.
TF Mastercard Gold
Annual fee
€0
Cash withdrawal
25.09%
In Germany
Interest accrues immediately from withdrawal: 25.09% p. a.
Within Eurozone
Interest accrues immediately from withdrawal: 25.09% p. a.
In foreign currency within EEA
Interest accrues immediately from withdrawal: 25.09% p. a.
Outside EEA / worldwide
Interest accrues immediately from withdrawal: 25.09% p. a.
eff. interest rate
25.09%
No annual fee
Free worldwide
Interest-free purchases within 51 days
Repayment in small monthly installments
Free travel insurance
Cashback: Up to 5% at Booking.com, Urlaubsplus.de, Mietwagen.de & more
Advertising notice: provider links in this overview are affiliate links — we receive a commission from the provider for sign-ups made through them.
Gebührenfrei Mastercard Gold
Advanzia Gebührenfrei Mastercard Gold is also a great credit card for starters in Germany. It’s easily accessible to expats, and you don’t need a long financial history to get one. It has very similar conditions to the TF Mastercard Gold. The credit card has no annual fee, no flat ATM withdrawal fees, and no foreign currency fees. However, cash withdrawals accrue interest immediately from the day of the withdrawal. Additionally, it also comes with travel insurance and cashback on travel and rental car bookings.
Gebührenfrei Mastercard Gold
Annual fee
€0
Cash withdrawal
24.95%
In Germany
Interest accrues immediately from withdrawal: 24.95% p. a.
Within Eurozone
Interest accrues immediately from withdrawal: 24.95% p. a.
In foreign currency within EEA
€0 + 0% foreign transaction fee Interest accrues immediately from withdrawal: 24.95% p. a.
Outside EEA / worldwide
€0 + 0% foreign transaction fee Interest accrues immediately from withdrawal: 24.95% p. a.
eff. interest rate
24.95%
No annual fee
Free worldwide
Interest-free in the first 7 weeks
Repayment in small monthly installments
Free travel insurance
Cashback: Up to 20% at Urlaubsplus.de, Mietwagen.de, Avis & more
Advertising notice: provider links in this overview are affiliate links — we receive a commission from the provider for sign-ups made through them.
Best Free Credit Cards for Established Expats
These cards offer the best conditions but require a long and clean credit history (Schufa).
awa7® Visa Card
The awa7® Visa Card is a sustainable, fee-free credit card in Germany that combines financial convenience with environmental responsibility. For every awa7® Visa credit card account opened, seven new trees and native shrubs are planted in Germany. In addition, a portion of the proceeds from card usage goes toward protecting and reforesting German forests. The card offers no annual fee, free cash withdrawals outside Germany for amounts of €50 or more, and no foreign transaction fees. Cash withdrawals at ATMs inside Germany cost €3.95 per transaction. It supports contactless payments and is compatible with Apple Pay and Google Pay. Flexible repayment options are available, with payments automatically debited from your existing bank account. While the card does not include built-in insurance, optional coverage can be added for an additional fee.
awa7® Visa
Annual fee
€0
Cash withdrawal
€3.95
In Germany
€3.95
Within Eurozone
€0
In foreign currency within EEA
€0
Outside EEA / worldwide
€0
Note
Withdrawing cash abroad incurs no fees from Hanseatic Bank. This applies to both ATMs and branches. ATM operators may impose their fees. With the Visa cash service, you can withdraw cash directly at the checkout when paying with your awa7® Visa credit card at participating retailers in Germany and without any additional fees.
eff. interest rate
21.96%
No annual fee
Completely free abroad
€4,000 immediate credit line
Travel insurance can be added additionally
Cashback: Up to 7% at Urlaubsplus.de
7 trees planted in Germany when you open an account
Advertising notice: provider links in this overview are affiliate links — we receive a commission from the provider for sign-ups made through them.
easybank Visa
The easybank Visa has no annual fee and an interest-free period of up to 59 days if you pay the statement in full. Paying in full by bank transfer or by instant debit in the app is free; automatic 100% repayment by monthly direct debit costs €2 per month (easybank, as of October 2026). The mobile banking app supports English, but phone-based customer support remains primarily in German. To apply, you need a current account with a German bank and a positive Schufa credit check, so the card suits expats who have already built a German credit history.
The easybank Gold Visa Card and the easybank Platinum card add insurance and travel benefits for an annual fee and have the same application requirements. Since 17 August 2026, new Platinum customers receive a Visa card only; the former Visa-and-Mastercard double is no longer issued.
Best Cashback Credit Cards in Germany
When it comes to cashback, the credit card that offers the most points or cashback rewards will rank the highest. With cashback programs, you can effectively earn money back on every purchase if you pay off the balance in a timely manner.
American Express Payback
While this credit card falls short in some areas compared to others, it does offer one of the better cashback rates in Germany.
In most cases, it doesn’t matter if the store is not a partner; you will still get cashback points for your purchases. It is a charge credit card, meaning that you cannot repay the borrowed amount in monthly installments.
1822direkt Visa Classic
Annual fee
€0
€36 from 2nd year on
Cash withdrawal
2%
In Germany
2% (min. €5.11)
Within Eurozone
€0
In foreign currency within EEA
2.25%
Outside EEA / worldwide
2.25%
min. €5.11
eff. interest rate
9.9%
Free cash withdrawals in the Eurozone
Free checking account with a monthly income of €700 or more
Withdrawing cash abroad incurs no fees from Hanseatic Bank. This applies to both ATMs and branches. ATM operators may impose their fees. With the Visa cash service, you can withdraw cash directly at the checkout when paying with your awa7® Visa credit card at participating retailers in Germany and without any additional fees.
eff. interest rate
21.96%
No annual fee
Completely free abroad
€4,000 immediate credit line
Travel insurance can be added additionally
Cashback: Up to 7% at Urlaubsplus.de
7 trees planted in Germany when you open an account
One Digital Mastercard Debit is included with bunq Free at no annual charge.
Cash withdrawal
€2.99
In Germany
€2.99
Within Eurozone
€2.99
In foreign currency within EEA
€2.99 + 0% currency conversion
Outside EEA / worldwide
€2.99 + 3% currency conversion
Note
Cash withdrawals cost €2.99 each and are only possible at ATMs that support contactless withdrawals through Apple Pay or Google Pay. ATM-operator fees may apply separately.
Free bank account with no monthly fee
Free Digital Mastercard Debit
German IBAN for customers signing up from Germany
English website, app and account-opening process
Apple Pay and Google Pay support
Up to 3.01% variable interest through the separate bunq Savings Account
Commerzbank Girocard with Visa function (business account)
Annual fee
€0
Priced per plan, see business account
Cash withdrawal
€2.50
In Germany
Free at Commerzbank and Cash Group ATMs (Deutsche Bank, UniCredit, Postbank) and at domestic ATMs that charge a direct fee (operator fee only); 1 % min. €5.98 elsewhere. The business accounts add a €2.50 posting fee per cash withdrawal (Premium Plus: 5 free per month) (price list dated 1 October 2026; business-account page).
Within Eurozone
1% (min. €5.98) 1 % min. €5.98 at other institutions without a direct customer fee; plus the business account's €2.50 posting fee per withdrawal where applicable (price list dated 1 October 2026).
In foreign currency within EEA
1% (min. €5.98) 1 % min. €5.98 plus the 0.59 % currency mark-up on the ECB reference rate (price list dated 1 October 2026).
Outside EEA / worldwide
1% (min. €5.98) 1 % min. €5.98; conversion per chapter E of the price list, no separate fee stated (price list dated 1 October 2026).
Note
Commerzbank girocard with additional Visa function (co-badge); included in the business accounts' base price (Klassik/Premium 1, Premium Plus 2) (business-account page, 30 Oct 2026).
Free at Deutsche Bank and Postbank branches; €3.95 per withdrawal at other providers' ATMs, plus any operator fee (Deutsche Bank price list dated 1 October 2026).
Within Eurozone
Free at Deutsche Bank Group branches abroad (currently Spain and Italy) and at cooperation partners (e.g. BNL Italy, BNP Paribas France, BGL Luxembourg); otherwise €3.95, plus any operator fee (Deutsche Bank price list dated 1 October 2026).
In foreign currency within EEA
€3.95 + 0.5% currency conversion €3.95 plus the 0.50 % currency mark-up; at cooperation partners only the mark-up (Deutsche Bank price list dated 1 October 2026).
Outside EEA / worldwide
€3.95 + 0.5% currency conversion €3.95 plus the 0.50 % currency mark-up; at cooperation partners (e.g. Barclays UK, Bank of America, Scotiabank, Westpac, TEB) only the mark-up (Deutsche Bank price list dated 1 October 2026).
Note
Debit card of the business accounts accepted at Mastercard ATMs; €10.00 a year, one card free with the Business BasicKonto and up to two with the Business ClassicKonto / PremiumKonto (Deutsche Bank price list dated 1 October 2026).
Free at Postbank ATMs and counters, at Deutsche Bank Group branches and via cash code at partner retailers' tills; €3.95 per withdrawal at other banks' ATMs, plus any operator fee (price list dated 4 May 2026).
Within Eurozone
Free at Deutsche Bank Group branches abroad (currently Spain and Italy) and at cooperation partners (e.g. BNL Italy, BNP Paribas France, BGL Luxembourg); otherwise €3.95 per withdrawal, plus any operator fee (price list dated 4 May 2026).
In foreign currency within EEA
€3.95 + 0.5% currency conversion At cooperation partners (e.g. Barclays UK, Bank of America, Scotiabank, Westpac, TEB) only the 0.50 % currency mark-up; otherwise €3.95 plus 0.50 %, plus any operator fee (price list dated 4 May 2026).
Outside EEA / worldwide
€3.95 + 0.5% currency conversion At cooperation partners (e.g. Barclays UK, Bank of America, Scotiabank, Westpac, TEB) only the 0.50 % currency mark-up; otherwise €3.95 plus 0.50 %, plus any operator fee (price list dated 4 May 2026).
Note
Business debit Mastercard of the business account; cash at other banks' counters 3 %, min. €5.00; default cash limit €1,000 per day, 7-day limit €3,000 (cards page); cash code at partner retailers' tills €0.00 (price list dated 4 May 2026).
Fee by the account's total monthly ATM volume across all cards: up to €500 1 %, €500–2,000 3 %, €2,000–5,000 5 %, above 8 %; recorded here as 1 % from the first euro (tariff list, version 20 Oct 2026).
Within Eurozone
Fee by the account's total monthly ATM volume across all cards: up to €500 1 %, €500–2,000 3 %, €2,000–5,000 5 %, above 8 %; recorded here as 1 % from the first euro (tariff list, version 20 Oct 2026).
In foreign currency within EEA
1% + 3% currency conversion* Fee by the account's total monthly ATM volume across all cards: up to €500 1 %, €500–2,000 3 %, €2,000–5,000 5 %, above 8 %; recorded here as 1 % from the first euro (tariff list, version 20 Oct 2026).
Outside EEA / worldwide
1% + 3% currency conversion* Fee by the account's total monthly ATM volume across all cards: up to €500 1 %, €500–2,000 3 %, €2,000–5,000 5 %, above 8 %; recorded here as 1 % from the first euro (tariff list, version 20 Oct 2026).
Note
ATM withdrawal limit €500 per card per month; card payment limit €100,000 per month (tariff list, version 20 Oct 2026).
2 free withdrawals per month included, then: €2 2 withdrawals per calendar month free at euro ATMs (Eurozone, fair-use policy, per account holder across all euro regions), €2.00 each further one; plus any direct operator fee (price list version 4.4, 26 June 2026).
Within Eurozone
2 free withdrawals per month included, then: €2 2 withdrawals per calendar month free at euro ATMs (Eurozone, fair-use policy, per account holder across all euro regions), €2.00 each further one; plus any direct operator fee (price list version 4.4, 26 June 2026).
In foreign currency within EEA
€0 + 1.7% currency conversion Foreign-currency withdrawals: no withdrawal fee, but a 1.7 % currency mark-up on the amount; plus any operator fee (price list version 4.4, 26 June 2026).
Outside EEA / worldwide
€0 + 1.7% currency conversion Foreign-currency withdrawals: no withdrawal fee, but a 1.7 % currency mark-up on the amount; plus any operator fee (price list version 4.4, 26 June 2026).
Note
Card payments worldwide in all currencies free, converted at the mid-market rate without mark-up; replacement card €10.00 (price list version 4.4, 26 June 2026).
eff. interest rate
13.4%
Virtual debit card included in the free Standard business account
2 free cash withdrawals per month in Germany
Unlimited free cash withdrawals in the EU
0.1% cashback on all purchases
Everything in English
Not usable if you already have a private account with N26
2% (min. €5) Free at Postbank ATMs and Deutsche Bank Group branches; 2.0 % min. €5.00 at other providers, plus any operator fee (Postbank Business Giro price information dated 1 June 2026).
Within Eurozone
2% (min. €5) Free at Deutsche Bank Group branches abroad and at cooperation partners; otherwise 2.0 % min. €5.00 (Postbank Business Giro price information dated 1 June 2026).
In foreign currency within EEA
2% (min. €5) + 0.5% currency conversion 2.0 % min. €5.00 plus the 0.50 % currency mark-up; at cooperation partners only the mark-up (Postbank Business Giro price information dated 1 June 2026).
Outside EEA / worldwide
2% (min. €5) + 0.5% currency conversion 2.0 % min. €5.00 plus the 0.50 % currency mark-up; at cooperation partners only the mark-up (Postbank Business Giro price information dated 1 June 2026).
Note
Debit Mastercard, €24.00 per year (Postbank Business Giro price information dated 1 June 2026).
Free at Postbank ATMs and counters and at Deutsche Bank branches; €3.95 per withdrawal at other banks' ATMs, plus any operator fee (Postbank Business Giro price information dated 1 June 2026).
Within Eurozone
Free at Deutsche Bank Group branches abroad (currently Spain and Italy) and at cooperation partners (e.g. BNL Italy, BNP Paribas France, BGL Luxembourg); otherwise €3.95 per withdrawal, plus any operator fee (Postbank Business Giro price information dated 1 June 2026).
In foreign currency within EEA
€3.95 + 0.5% currency conversion At cooperation partners only the 0.50 % currency mark-up; otherwise €3.95 plus 0.50 %, plus any operator fee (Postbank Business Giro price information dated 1 June 2026).
Outside EEA / worldwide
€3.95 + 0.5% currency conversion At cooperation partners (e.g. Barclays UK, Bank of America, Scotiabank, Westpac, TEB) only the 0.50 % currency mark-up; otherwise €3.95 plus 0.50 %, plus any operator fee (Postbank Business Giro price information dated 1 June 2026).
Note
Debit card of the Postbank Business Giro accepted at Mastercard ATMs; one card per account free, each further €6.00 p.a. (Businesskonto) or €12.00 p.a. (Geschäftskonto) (Postbank Business Giro price information dated 1 June 2026).
Qonto One Card
Annual fee
€0
Cash withdrawal
€2
In Germany
€2
Within Eurozone
€2
In foreign currency within EEA
€2 + 2% currency conversion*
Outside EEA / worldwide
€2 + 2% currency conversion*
Note
Withdrawal limit €1,000 per card per calendar month; card payment limit €20,000 per card per calendar month (price list dated 3 August 2026).
Card payments of up to €20,000 per calendar month
German IBAN available through the linked Qonto business account
Adjustable payment limits and real-time notifications
One cash withdrawal included per month
Only one cash withdrawal included per month; additional withdrawals cost €2 excluding VAT
Up to €250 per month per account free, 2.69 % of the amount above; the allowance is account-wide across all cards and regions (Wise Business pricing and card-fee pages for businesses in Germany, 30 Oct 2026).
Within Eurozone
Up to €250 per month per account free, 2.69 % of the amount above; the allowance is account-wide across all cards and regions (Wise Business pricing and card-fee pages for businesses in Germany, 30 Oct 2026).
In foreign currency within EEA
Up to €250 per month per account free, 2.69 % of the amount above; the allowance is account-wide across all cards and regions; conversion into a currency not held at the mid-market rate plus a variable exchange fee (from 0.2 %, per currency), not recorded as a rate here (Wise Business pricing and card-fee pages for businesses in Germany, 30 Oct 2026).
Outside EEA / worldwide
Up to €250 per month per account free, 2.69 % of the amount above; the allowance is account-wide across all cards and regions; conversion into a currency not held at the mid-market rate plus a variable exchange fee (from 0.2 %, per currency), not recorded as a rate here (Wise Business pricing and card-fee pages for businesses in Germany, 30 Oct 2026).
Note
First card free, each employee card €4 one-time, replacement €4, digital cards free; payments in a held currency free, otherwise conversion at the mid-market rate plus a fee from 0.2 %; funding external e-wallets 2 % (Wise Business pricing and card-fee pages for businesses in Germany, 30 Oct 2026).
€2.99 per withdrawal (bunq fee information for private and business customers, 15 Oct 2026).
Within Eurozone
€2.99 per withdrawal (bunq fee information for private and business customers, 15 Oct 2026).
In foreign currency within EEA
€2.99 + 0.5% currency conversion €2.99 per withdrawal; plus a 0.5 % network fee where a conversion is needed (bunq fee information for private and business customers, 15 Oct 2026).
Outside EEA / worldwide
€2.99 + 0.5% currency conversion €2.99 per withdrawal; plus a 0.5 % network fee where a conversion is needed (bunq fee information for private and business customers, 15 Oct 2026).
Note
The record holds bunq Free Business; Core, Pro and Elite Business carry their own rates. Foreign-currency payments at the real Mastercard rate incl. 0.5 % protection; on Free this covers €1,000 a year, 1.5 % beyond. Replacement card €9.99 (Pro/Elite: 1 a year free), Metal Card €99 (bunq fee information for private and business customers, 15 Oct 2026).
bunq Metal Mastercard
Annual fee
€0
Cash withdrawal
n/a
In Germany
n/a
Within Eurozone
n/a
In foreign currency within EEA
n/a
Outside EEA / worldwide
n/a
Physical and virtual Mastercard account, debit included
Free at domestic Deutsche Bank and Postbank branches; €3.95 at other providers, plus any operator fee (Deutsche Bank price list dated 1 October 2026).
Within Eurozone
Free at cooperation partners abroad (euro withdrawals); €3.95 at other providers (Deutsche Bank price list dated 1 October 2026).
In foreign currency within EEA
€3.95 + 0.5% currency conversion €3.95 plus the 0.50 % currency mark-up; at cooperation partners only the mark-up (Deutsche Bank price list dated 1 October 2026).
Outside EEA / worldwide
€3.95 + 0.5% currency conversion €3.95 plus the 0.50 % currency mark-up; at cooperation partners only the mark-up (Deutsche Bank price list dated 1 October 2026).
Note
Debit Mastercard, €24.00 a year; replacement card free (Deutsche Bank price list dated 1 October 2026).
2.5% (min. €5.75) 2.5 % min. €5.75 at ATMs; 3.0 % min. €5.75 at counters (Deutsche Bank price list dated 1 October 2026).
Within Eurozone
2.5% (min. €5.75) 2.5 % min. €5.75 at ATMs; 3.0 % min. €5.75 at counters (Deutsche Bank price list dated 1 October 2026).
In foreign currency within EEA
2.5% (min. €5.75) + 1.75% foreign transaction fee + 0.5% currency conversion 2.5 % min. €5.75 plus 1.75 % min. €1.50 in foreign currency and the 0.50 % currency mark-up (Deutsche Bank price list dated 1 October 2026).
Outside EEA / worldwide
2.5% (min. €5.75) + 1.75% foreign transaction fee + 0.5% currency conversion 2.5 % min. €5.75 plus 1.75 % min. €1.50 outside the EU/EEA or in foreign currency and the 0.50 % currency mark-up (Deutsche Bank price list dated 1 October 2026).
Note
Credit card (Mastercard or VISA), €29.00 a year; replacement card free (Deutsche Bank price list dated 1 October 2026).
2% (min. €5) 2.0 % min. €5.00 at ATMs (Postbank's included); 3.0 % min. €5.00 at counters (Postbank Business Giro price information dated 1 June 2026).
Within Eurozone
2% (min. €5) 2.0 % min. €5.00 at ATMs; 3.0 % min. €5.00 at counters (Postbank Business Giro price information dated 1 June 2026).
In foreign currency within EEA
2% (min. €5) + 1.85% foreign transaction fee + 0.5% currency conversion 2.0 % min. €5.00 plus 1.85 % in foreign currency plus the 0.50 % currency mark-up (Postbank Business Giro price information dated 1 June 2026).
Outside EEA / worldwide
2% (min. €5) + 1.85% foreign transaction fee + 0.5% currency conversion 2.0 % min. €5.00 plus 1.85 % outside the EU/EEA or in foreign currency plus the 0.50 % currency mark-up (Postbank Business Giro price information dated 1 June 2026).
Note
Credit card, €30.00 per year, €0.00 in the first year when opened together with a Postbank Business Giro; each further card €30.00 p.a. (Postbank Business Giro price information dated 1 June 2026).
1.95% (min. €5.98) 1.95 % of the amount, minimum €5.98, at every ATM; plus any ATM operator fee (card price list dated 31 August 2023).
Within Eurozone
1.95% (min. €5.98) 1.95 % of the amount, minimum €5.98, at every ATM; plus any ATM operator fee (card price list dated 31 August 2023).
In foreign currency within EEA
1.95% (min. €5.98) + 1.5% foreign transaction fee + 0.59% currency conversion 1.95 % min. €5.98 plus the 1.5 % foreign-use fee (outside the euro area) and the 0.59 % currency mark-up for EEA currencies (card price list dated 31 August 2023).
Outside EEA / worldwide
1.95% (min. €5.98) + 1.5% foreign transaction fee 1.95 % min. €5.98 plus the 1.5 % foreign-use fee outside the euro area; conversion per chapter E of the price list (card price list dated 31 August 2023).
Note
Cash limit €1,000 per day, max. €2,000 per week; replacement card €12.50 (delivery within Europe) (card price list dated 31 August 2023).
3 free withdrawals per month included, then: €2 3 withdrawals per calendar month free at euro ATMs (Eurozone, fair-use policy, per account holder across all euro regions), €2.00 each further one; plus any direct operator fee (price list version 4.4, 26 June 2026).
Within Eurozone
3 free withdrawals per month included, then: €2 3 withdrawals per calendar month free at euro ATMs (Eurozone, fair-use policy, per account holder across all euro regions), €2.00 each further one; plus any direct operator fee (price list version 4.4, 26 June 2026).
In foreign currency within EEA
€0 + 1.7% currency conversion Foreign-currency withdrawals: no withdrawal fee, but a 1.7 % currency mark-up on the amount; plus any operator fee (price list version 4.4, 26 June 2026).
Outside EEA / worldwide
€0 + 1.7% currency conversion Foreign-currency withdrawals: no withdrawal fee, but a 1.7 % currency mark-up on the amount; plus any operator fee (price list version 4.4, 26 June 2026).
Note
Card payments worldwide in all currencies free, converted at the mid-market rate without mark-up; replacement card €10.00 (price list version 4.4, 26 June 2026).
eff. interest rate
13.4%
Debit card in 5 colors included in the Smart business account
3 free cash withdrawals per month in Germany
Unlimited free cash withdrawals in the EU
0.1% cashback on all purchases
Everything in English
Not usable if you already have a private account with N26
€4.90/month for the Smart business account
1.7% cash withdrawals in foreign currency
N26 Smart Mastercard
Annual fee
€58.80
Cash withdrawal
€0
In Germany
3 free withdrawals per month included, then: €2
Within Eurozone
€2
In foreign currency within EEA
€0 + 1.7% currency conversion
Outside EEA / worldwide
€0 + 1.7% currency conversion
eff. interest rate
13.4%
Mastercard debit in 5 colors included in the Smart plan
1.95% (min. €5.98) 1.95 % of the amount, minimum €5.98, at every ATM; plus any ATM operator fee (card price list dated 31 August 2023).
Within Eurozone
1.95% (min. €5.98) 1.95 % of the amount, minimum €5.98, at every ATM; plus any ATM operator fee (card price list dated 31 August 2023).
In foreign currency within EEA
1.95% (min. €5.98) + 1.5% foreign transaction fee + 0.59% currency conversion 1.95 % min. €5.98 plus the 1.5 % foreign-use fee (outside the euro area) and the 0.59 % currency mark-up for EEA currencies (card price list dated 31 August 2023).
Outside EEA / worldwide
1.95% (min. €5.98) + 1.5% foreign transaction fee 1.95 % min. €5.98 plus the 1.5 % foreign-use fee outside the euro area; conversion per chapter E of the price list (card price list dated 31 August 2023).
Note
Cash limit €1,000 per day, max. €2,000 per week; replacement card €12.50 (delivery within Europe) (card price list dated 31 August 2023).
2.5% (min. €5.75) 2.5 % min. €5.75 at domestic ATMs; 3.0 % min. €5.75 at counters (Deutsche Bank price list dated 1 October 2026).
Within Eurozone
Free of charge by Deutsche Bank at foreign providers' ATMs (operator fee possible); 3.0 % min. €5.75 at counters (Deutsche Bank price list dated 1 October 2026).
In foreign currency within EEA
€0 + 1.75% foreign transaction fee + 0.5% currency conversion Free by Deutsche Bank at ATMs, plus 1.75 % min. €1.50 in foreign currency and the 0.50 % currency mark-up (Deutsche Bank price list dated 1 October 2026).
Outside EEA / worldwide
€0 + 1.75% foreign transaction fee + 0.5% currency conversion Free by Deutsche Bank at ATMs, plus 1.75 % min. €1.50 outside the EU/EEA or in foreign currency and the 0.50 % currency mark-up (Deutsche Bank price list dated 1 October 2026).
Note
Credit card with PLUS package, €79.00 a year; cash at foreign providers' ATMs free of charge by Deutsche Bank (Deutsche Bank price list dated 1 October 2026).
1.95% (min. €5.98) 1.95 % of the amount, minimum €5.98, at every ATM; plus any ATM operator fee (card price list dated 31 August 2023).
Within Eurozone
1.95% (min. €5.98) 1.95 % of the amount, minimum €5.98, at every ATM; plus any ATM operator fee (card price list dated 31 August 2023).
In foreign currency within EEA
1.95% (min. €5.98) + 1.5% foreign transaction fee + 0.59% currency conversion 1.95 % min. €5.98 plus the 1.5 % foreign-use fee (outside the euro area) and the 0.59 % currency mark-up for EEA currencies (card price list dated 31 August 2023).
Outside EEA / worldwide
1.95% (min. €5.98) + 1.5% foreign transaction fee 1.95 % min. €5.98 plus the 1.5 % foreign-use fee outside the euro area; conversion per chapter E of the price list (card price list dated 31 August 2023).
Note
Cash limit €1,000 per day, max. €2,000 per week; replacement card €12.50 (delivery within Europe) (card price list dated 31 August 2023).
2% (min. €5) 2.0 % min. €5.00 at ATMs (Postbank's included); 3.0 % min. €5.00 at counters (Postbank Business Giro price information dated 1 June 2026).
Within Eurozone
2% (min. €5) 2.0 % min. €5.00 at ATMs; 3.0 % min. €5.00 at counters (Postbank Business Giro price information dated 1 June 2026).
In foreign currency within EEA
2% (min. €5) + 1.85% foreign transaction fee + 0.5% currency conversion 2.0 % min. €5.00 plus 1.85 % in foreign currency plus the 0.50 % currency mark-up (Postbank Business Giro price information dated 1 June 2026).
Outside EEA / worldwide
2% (min. €5) + 1.85% foreign transaction fee + 0.5% currency conversion 2.0 % min. €5.00 plus 1.85 % outside the EU/EEA or in foreign currency plus the 0.50 % currency mark-up (Postbank Business Giro price information dated 1 June 2026).
Note
Credit card, €80.00 per year, €40.00 in the first year when opened together with a Postbank Business Giro; each further card €80.00 p.a. (Postbank Business Giro price information dated 1 June 2026).
Fee by the account's total monthly ATM volume across all cards: up to €500 0 %, €500–2,000 1 %, €2,000–5,000 5 %, above 8 % (tariff list, version 20 Oct 2026).
Within Eurozone
Fee by the account's total monthly ATM volume across all cards: up to €500 0 %, €500–2,000 1 %, €2,000–5,000 5 %, above 8 % (tariff list, version 20 Oct 2026).
In foreign currency within EEA
1% + 2% currency conversion* Fee by the account's total monthly ATM volume across all cards: up to €500 0 %, €500–2,000 1 %, €2,000–5,000 5 %, above 8 % (tariff list, version 20 Oct 2026).
Outside EEA / worldwide
1% + 2% currency conversion* Fee by the account's total monthly ATM volume across all cards: up to €500 0 %, €500–2,000 1 %, €2,000–5,000 5 %, above 8 % (tariff list, version 20 Oct 2026).
Note
Foreign-currency card payments free up to €500 per month, 2 % above; ATM withdrawal limit €2,000 per card per month; card payment limit €100,000 per month (tariff list, version 20 Oct 2026).
5 free cash withdrawals per month (per card, not per region); withdrawal limit €2,000 per card per calendar month; card payment limit €40,000 per card per calendar month (price list dated 3 August 2026).
Card payment limit of up to €40,000 per calendar month
0.4% cashback on eligible purchases, up to €15 per month or €180 per year
Five cash withdrawals included per month
Apple Pay and Google Pay support
Cashback applies only to eligible purchases and is capped at €15 per company per month
5 free withdrawals per month included, then: €2 5 withdrawals per calendar month free at euro ATMs (Eurozone, fair-use policy, per account holder across all euro regions), €2.00 each further one; plus any direct operator fee (price list version 4.4, 26 June 2026).
Within Eurozone
5 free withdrawals per month included, then: €2 5 withdrawals per calendar month free at euro ATMs (Eurozone, fair-use policy, per account holder across all euro regions), €2.00 each further one; plus any direct operator fee (price list version 4.4, 26 June 2026).
In foreign currency within EEA
Foreign-currency withdrawals free of charge by N26 at the mid-market rate; plus any operator fee (price list version 4.4, 26 June 2026).
Outside EEA / worldwide
Foreign-currency withdrawals free of charge by N26 at the mid-market rate; plus any operator fee (price list version 4.4, 26 June 2026).
Note
Card payments worldwide in all currencies free, converted at the mid-market rate without mark-up; replacement card €10.00 (price list version 4.4, 26 June 2026).
eff. interest rate
13.4%
Debit card in 5 colors included in the Go business account
5 free cash withdrawals per month in Germany
Unlimited free cash withdrawals elsewhere
0.1% cashback on all purchases
Travel insurance
Everything in English
Not usable if you already have a private account with N26
€9.90/month for the Go business account
N26 Go Mastercard
Annual fee
€118.80
Cash withdrawal
€0
In Germany
5 free withdrawals per month included, then: €2
Within Eurozone
€0
In foreign currency within EEA
€2 + 0% foreign transaction fee
Outside EEA / worldwide
€0 + 0% foreign transaction fee
eff. interest rate
13.4%
Mastercard debit in 5 colors included in the Go plan
Mobile bank account
5 free cash withdrawals per month in Germany and the EU
8 free withdrawals per month included, then: €2 8 withdrawals per calendar month free at euro ATMs (Eurozone, fair-use policy, per account holder across all euro regions), €2.00 each further one; plus any direct operator fee (price list version 4.4, 26 June 2026).
Within Eurozone
8 free withdrawals per month included, then: €2 8 withdrawals per calendar month free at euro ATMs (Eurozone, fair-use policy, per account holder across all euro regions), €2.00 each further one; plus any direct operator fee (price list version 4.4, 26 June 2026).
In foreign currency within EEA
Foreign-currency withdrawals free of charge by N26 at the mid-market rate; plus any operator fee (price list version 4.4, 26 June 2026).
Outside EEA / worldwide
Foreign-currency withdrawals free of charge by N26 at the mid-market rate; plus any operator fee (price list version 4.4, 26 June 2026).
Note
Card payments worldwide in all currencies free, converted at the mid-market rate without mark-up; replacement card €10.00 (price list version 4.4, 26 June 2026).
eff. interest rate
13.4%
Metal debit card in 3 colors included in the Metal business account
8 free cash withdrawals per month in Germany
Unlimited free cash withdrawals elsewhere
0.5% cashback on all purchases
Travel & lifestyle insurance
Everything in English
Not usable if you already have a private account with N26
€16.90/month for the Metal business account
N26 Metal Mastercard
Annual fee
€202.80
Cash withdrawal
€0
In Germany
8 free withdrawals per month included, then: €2
Within Eurozone
€0
In foreign currency within EEA
€2 + 0% foreign transaction fee
Outside EEA / worldwide
€0 + 0% foreign transaction fee
eff. interest rate
13.4%
Metal Mastercard debit in 3 colors included in the Metal plan
Unlimited free cash withdrawals; withdrawal limit €3,000 per card per calendar month; card payment limit €200,000 per card per calendar month (price list dated 3 August 2026).
Card payment limit of up to €200,000 per calendar month
No Qonto foreign-exchange fee on non-euro card payments
0.8% cashback on eligible purchases, up to €30 per month or €360 per year
Premium insurance and assistance coverage
Apple Pay and Google Pay support
Cashback is limited to eligible purchases and capped at €30 per company per month
Costs €20 per month excluding VAT in addition to the Qonto plan
Fee by the account's total monthly ATM volume across all cards: up to €2,000 0 %, €2,000–5,000 3 %, €5,000–10,000 5 %, above 8 % (tariff list, version 20 Oct 2026).
Within Eurozone
Fee by the account's total monthly ATM volume across all cards: up to €2,000 0 %, €2,000–5,000 3 %, €5,000–10,000 5 %, above 8 % (tariff list, version 20 Oct 2026).
In foreign currency within EEA
3% + 1% currency conversion* Fee by the account's total monthly ATM volume across all cards: up to €2,000 0 %, €2,000–5,000 3 %, €5,000–10,000 5 %, above 8 % (tariff list, version 20 Oct 2026).
Outside EEA / worldwide
3% + 1% currency conversion* Fee by the account's total monthly ATM volume across all cards: up to €2,000 0 %, €2,000–5,000 3 %, €5,000–10,000 5 %, above 8 % (tariff list, version 20 Oct 2026).
Note
Foreign-currency card payments free up to €500 per month, 1 % above; ATM withdrawal limit €5,000 per card per month; card payment limit €100,000 per month (tariff list, version 20 Oct 2026).
Fee by the account's total monthly ATM volume across all cards: up to €2,000 0 %, €2,000–5,000 3 %, €5,000–10,000 5 %, above 8 % (tariff list, version 20 Oct 2026).
Within Eurozone
Fee by the account's total monthly ATM volume across all cards: up to €2,000 0 %, €2,000–5,000 3 %, €5,000–10,000 5 %, above 8 % (tariff list, version 20 Oct 2026).
In foreign currency within EEA
3% + 1% currency conversion* Fee by the account's total monthly ATM volume across all cards: up to €2,000 0 %, €2,000–5,000 3 %, €5,000–10,000 5 %, above 8 % (tariff list, version 20 Oct 2026).
Outside EEA / worldwide
3% + 1% currency conversion* Fee by the account's total monthly ATM volume across all cards: up to €2,000 0 %, €2,000–5,000 3 %, €5,000–10,000 5 %, above 8 % (tariff list, version 20 Oct 2026).
Note
Foreign-currency card payments free up to €1,000 per month, 1 % above (Grow: 0 %); ATM withdrawal limit €5,000 per card per month; card payment limit €100,000 per month (Grow €200,000) (tariff list, version 20 Oct 2026).
Advertising notice: provider links in this overview are affiliate links — we receive a commission from the provider for sign-ups made through them.
Best Student Credit Cards in Germany
Students coming to Germany will typically not have a long credit history or complete documents. Their financial situation will also be limited compared to most. Therefore, the best credit cards for students will be those with high approval rates that offer the benefits of financial flexibility.
Without a German credit history, a debit card such as the N26 Standard Mastercard or the Trade Republic Visa Debit Card is the simplest start: both work for card payments worldwide without a credit line. More options are in our guide to credit cards without Schufa.
Best Travel Credit Cards in Germany
The best credit cards for travel are those that offer travel insurance, miles, discounts, airport lounge access, no foreign currency fees, and affordable cash withdrawals abroad. With an established German credit history, the easybank Visa adds no foreign currency fees on purchases and an interest-free period of up to 59 days. See our best travel credit cards in Germany comparison for more options.
Best Business Credit Cards in Germany
Business credit cards in Germany may offer cashback, travel rewards, or discounts on expenses such as office supplies and business travel. See our best business credit cards in Germany comparison for suitable options.
How to Get a German Credit Card: A Step-by-Step Guide
To verify your identity, you may be required to participate in a video call with a customer service agent.Photo: iStock.com/fizkes
Step 1: Check Your Eligibility
As with any product, each credit card will have its eligibility requirements. The most common eligibility requirements for a credit card in Germany are that you must have at least a German bank account, a German phone number, a valid passport, and be at least 18 years old. Non-EU citizens may also require a residence permit and a work permit for Germany.
To check your eligibility for the credit card you’re interested in, simply follow the link to their application page.
Step 2: Fill out the Online Application Form
Online credit card applications will request your personal details. This includes your name, address, birthdate, and contact information. If you’re asking for a certain credit limit, you must include information about your income in your application.
Step 3: Pass Video Identification Process
After submitting your online application form, the next step is to wait for the credit card bank to contact you using the contact information you provided. Once they contact you, you must verify your identity with them. How this is done would depend on the bank in question, but typically, the application process involves a video call with their customer service agent.
After your identity is verified, you will receive the credit card along with an activation letter, which contains important information and steps to activate your account.
Conclusion
Credit cards are a great way to expand your financial freedom when used and managed wisely. It is also one of the few financial tools available that provide you with more benefits and advantages the longer you have it and the more you use it.
The credit cards listed above all offer excellent benefits. For beginners, the TF Bank Mastercard Gold is the best choice: it is generally easier to get, even with a limited German credit history, but cash withdrawals accrue interest from the day of the withdrawal. For established expats with a German credit history, the Amex credit cards are the best choices. Choosing the right free credit card or a credit card offer subject to fees depends on your personal needs, spending habits, and how you plan to use it in everyday life.
If you’re considering getting a credit card and intend to use the installment repayment feature, it’s crucial to research the interest rates first. This will help you understand how cost-effective the card is for your specific needs. When conducting a credit card comparison, the effective annual interest rate is the most reliable figure.
Yes, foreigners can get a credit card in Germany. However, expats often face more hurdles than German citizens. Many banks require a German credit history (Schufa), a registered address, stable income, and a local bank account. Newcomers frequently lack these, making approval for traditional credit cards more difficult. As an alternative, many expats start with a debit or prepaid card, which may not require a Schufa check.
Free credit cards are usually advertised as having no annual or monthly fees. However, this doesn’t mean they are completely free from charge. Many free credit cards still charge fees for specific transactions, particularly for payments made in foreign currencies or cash withdrawals at ATMs. A credit card is truly free only if it has no annual fee and supports worldwide free payments and charge-free withdrawals.
Visa and Mastercard are widely accepted in Germany, especially in larger stores, supermarkets, restaurants, hotels, and online shops. However, some smaller businesses may not accept credit cards at all, or only for purchases above a minimum amount.
American Express and Diners Club cards are accepted far less frequently. Many merchants exclude them due to higher transaction fees, so it’s also advisable to carry a Visa or Mastercard. Contactless payments using NFC-enabled credit cards or mobile wallets, such as Apple Pay or Google Pay, are increasingly popular in Germany and are often accepted even when traditional card payments are not explicitly advertised.
There are 4 different types of credit cards in Germany: charge credit cards, revolving credit cards, debit cards, and prepaid credit cards.
A charge credit card compiles all purchase payments, typically within 30 days. After this period, a credit card statement is generated, which the owner must pay directly.
A revolving credit card is a type of credit card that provides its owners with a line of credit to use, allowing them to repay the balance in monthly installments with an interest rate applied to the outstanding balance.
A debit card is directly associated with the owner’s current account. Each time the debit card is used, the amount is automatically deducted from the linked bank account.
To use a prepaid card, you must first transfer money to the card. For this, you do not necessarily need a German bank account.
The most common type of credit card in Germany is the charge credit card. Charge credit cards require the cardholder to pay the outstanding balance in full at the end of each month, rather than carrying a balance over time. Debit cards rank second. Revolving credit cards and prepaid cards play a relatively minor role in Germany.
For beginners, the TF Bank Mastercard Gold is generally easier to get, even with a limited German credit history, but cash withdrawals accrue interest from the day of the withdrawal. With an established Schufa record and a regular income, the American Express cards add rewards: the Blue Card has no annual fee, the Gold and Platinum Cards add travel insurance and Membership Rewards points. Without any German credit history, a debit card such as the N26 Standard Mastercard or the Trade Republic Visa Debit Card is the simplest start.
The easiest credit card to get approved for is one that is not strict with your credit history, among other requirements. Based on our research, these are TF Bank Mastercard Gold and Gebührenfrei Mastercard Gold. Both cards are, therefore, also well suited for newcomers who do not yet have a long credit history in Germany.
Yes, most German credit cards use strong authentication systems for online payments, including Mastercard Identity Check and Visa Secure. These systems add an extra layer of protection by requiring a verification code or app confirmation during the checkout process.
Share
About the authors
Janine El-SaghirJanine El Saghir is an editor at How-to-Germany.com, where she specializes in the practical aspects of daily life and integration for expatriates. With years of...Read more
Erkan BogaErkan Boga is the founder and CEO of qmedia GmbH, the publishing house behind How-to-Germany.com. He established the platform with the clear vision of creating...Read more
Sadie VossContent Lead & EditorSadie Voss is the Lead Editor for How-to-Germany.com. As an expat who carved her own way into Berlin from the United States, Sadie is deeply...Read more

 Written by
 Reviewed by
 Edited by